Credit Card Lost or Stolen: What Should You Do and Who Pays?
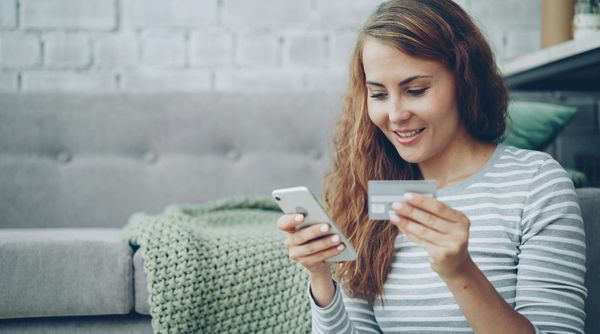
Losing a credit card or discovering an unauthorized transaction can be stressful. However, cardholders may not always be responsible for paying the entire amount involved in a fraudulent transaction. Under Reserve Bank of India (RBI) rules, the customer’s liability depends on factors such as whether the customer was negligent and how quickly the bank was informed.
If an unauthorized electronic transaction is reported to the bank within three working days of receiving the communication about the transaction, and there is no customer negligence, the customer’s liability can be zero under the applicable RBI framework.
Therefore, if your credit card is lost or you notice a transaction that you did not make, do not wait for the monthly statement. Contact the bank immediately through its official helpline, mobile app or other authorized channels and request that the card be blocked.
What If the Customer Was Negligent?
If the loss occurred because the customer shared sensitive security information such as the card PIN, password or other credentials, the customer may be responsible for the loss until the bank is informed. However, transactions taking place after the customer has reported the unauthorized use to the bank are generally treated differently under the RBI framework.
What Happens If You Report It After 3 Days?
If an unauthorized transaction is reported after three working days but within seven working days, the customer’s liability may be limited according to the applicable RBI rules. If the delay exceeds seven working days, the customer’s liability is determined according to the bank’s board-approved policy.
This makes it important to report a lost card or unauthorized transaction as soon as possible rather than waiting for the next credit card statement.
Keep Records of Your Complaint
After reporting the issue to the bank, keep the complaint reference number, SMS or email confirmation and details of the unauthorized transaction safely. If the bank requests any documents or a written declaration, submit them promptly.
Blocking the credit card immediately is also important because it can help prevent further unauthorized use.
Keep Transaction Alerts Active
Credit cardholders should keep SMS and other transaction alerts enabled. These notifications can help identify unauthorized transactions quickly and allow timely action.
Card statements should also be reviewed regularly. If the complaint is not resolved satisfactorily by the bank, customers can use the applicable RBI complaint mechanism after following the bank’s internal grievance process.
Top Stories
-
 Avinash Becomes the New Captain of the House22/Sep/2026 1:05:04 PM
-
 LPG Subsidy: Aadhaar Biometric Authentication Required from October 122/Sep/2026 12:59:26 PM
-
Credit Card Lost or Stolen: What Should You Do and Who Pays?22/Sep/2026 12:24:21 PM
-
 Tesla Chennai Showroom: New Experience Centre to Open This Week22/Sep/2026 12:19:21 PM
-
 Best 5 Places to Visit in and Around West Mambalam, Chennai22/Sep/2026 12:16:03 PM
-
 Fake SIM Card Documents: Up to 3 Years Jail and ₹50 Lakh Fine22/Sep/2026 12:03:19 PM