What Happens If Gold Prices Fall After Taking a Gold Loan? Key Risks Every Borrower Should Know
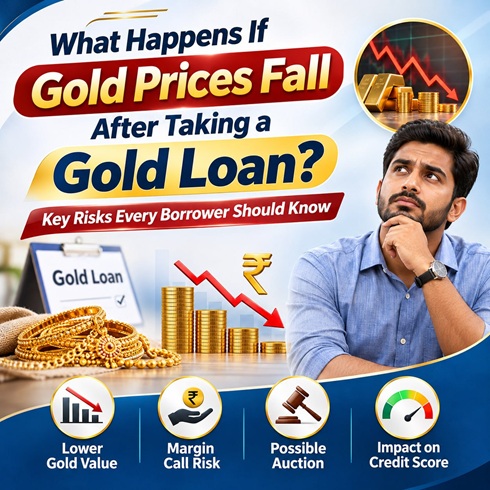
Gold price fluctuations can affect your gold loan`s Loan-to-Value (LTV) ratio, potentially triggering margin calls or additional repayment requirements. Here`s what borrowers need to know to protect their pledged jewellery.
Gold loans are a popular borrowing option in India, offering quick access to funds against pledged jewellery. However, a sudden decline in gold prices can create financial challenges for borrowers.
While falling gold prices do not automatically increase the loan amount, they reduce the value of the pledged collateral. This can affect the Loan-to-Value (LTV) ratio and prompt lenders to take corrective action.
How Falling Gold Prices Affect Your Gold Loan
When borrowers apply for a , lenders determine the eligible amount based on the assessed value of their gold and applicable LTV limits.
For example, under a 75% LTV limit, gold worth ₹1,00,000 can secure a loan of ₹75,000.
If gold prices decline by 10%, the pledged gold`s value falls to ₹90,000. However, the outstanding loan remains ₹75,000, increasing the LTV ratio to approximately 83.3%.
This increase may exceed the lender`s permitted threshold, requiring borrowers to take corrective measures.
What Is a Margin Call in a Gold Loan?
A margin call occurs when the outstanding loan exceeds the acceptable proportion of the pledged gold`s value.
Depending on the loan agreement and applicable regulations, lenders may ask borrowers to:
- Repay part of the outstanding loan.
- Pledge additional gold as collateral.
- Clear accumulated interest to reduce the outstanding balance.
Borrowers generally receive a specified period to respond. The exact requirements depend on the lender`s policies and applicable RBI gold loan regulations.
Can Lenders Auction Your Gold?
If borrowers fail to address repayment obligations or margin requirements, lenders may initiate recovery proceedings, including auctioning pledged jewellery in accordance with applicable rules.
The process generally involves prior notices, reminders and an auction conducted under the lender`s published auction policy
After recovering the outstanding loan, interest and applicable charges, any surplus auction proceeds must be returned to the borrower.
Loan defaults may also negatively affect credit scores if reported to credit bureaus.
Example: How a 12% Gold Price Drop Affects Borrowers
Consider a borrower who pledges gold worth ₹5,00,000 and receives a loan of ₹3,75,000 at 75% LTV.
If gold prices decline by 12%, the collateral value drops to ₹4,40,000.
The LTV immedediately increases to approximately 85.2%. With accumulated interest, it could rise further, potentially reaching around 88%.
The lender may then request partial repayment or additional collateral to restore the required margin.
How Can Gold Loan Borrowers Reduce Their Risk?
Financial planning can help borrowers manage gold price fluctuations without unnecessary pressure.
Borrowing only 60-65% of the pledged gold`s value, rather than the maximum available amount, provides an additional safety cushion.
Borrowers should also monitor gold prices periodically, maintain emergency funds, pay interest on time and consider partial prepayments when financially possible.
Using a gold loan calculatorcan help estimate borrowing eligibility based on current gold values.
Final Takeaway
A decline in gold prices does not automatically result in the loss of pledged jewellery. However, it can increase the LTV ratio and create additional repayment obligations.
Understanding lender policies, monitoring outstanding dues and responding promptly to official notices can help borrowers protect their gold and maintain financial stability.
Top Stories
-
-
 Tamil Nadu School Education Department: 5-Year Rule: Employees Must Clear Departmental Exams17/Nov/2026 1:02:09 PM
-
 Tamil Nadu Terrace Garden Scheme 2026: How to Apply Online for Subsidy17/Nov/2026 12:39:06 PM
-
-
-
 US Student Visa Rules 2026: Court Strikes Down New Visa Policy for Foreign Students17/Nov/2026 11:52:57 AM
 JB Soft System