NRI Tax Return: How to Correct Wrong Capital Gains Exemption Claims Under India-UAE Tax Treaty
NRIs who incorrectly claim capital gains tax exemptions on Indian shares may need to file an updated income-tax return and pay applicable tax and interest. While certain mutual fund gains may qualify for relief under the India-UAE tax treaty, gains from shares in Indian companies are taxable in India under the relevant treaty provisions.
Non-Resident Indians (NRIs) investing in Indian shares and mutual funds should carefully check their capital gains tax liabilities before claiming exemptions in their income-tax returns. Incorrect claims under the India-UAE Double Taxation Avoidance Agreement (DTAA) can lead to additional tax liabilities and the need to correct previously filed returns.
For eligible taxpayers, filing an Updated Income Tax Return (ITR-U) may provide an opportunity to correct certain errors when the deadline for filing a revised return has expired.
India-UAE Tax Treaty: Different Rules for Shares and Mutual Funds
Under Indian income-tax laws, income received or deemed to be received in India, as well as income accruing or arising or deemed to accrue or arise in India, may be taxable in India. Capital gains from the transfer of Indian shares and mutual fund units may therefore fall within the Indian tax framework.
However, eligible NRIs may claim relief under the India-UAE DTAA, depending on the nature of their investments, residential status and the applicable treaty provisions.
The tax treatment differs between shares and mutual fund units.
Capital gains from shares: Under the India-UAE tax treaty, capital gains arising from the transfer of shares in an Indian company are taxable in India. Consequently, NRIs cannot automatically claim exemption from Indian capital gains tax on these investments merely because they reside in the UAE.
Capital gains from mutual funds: Gains from the transfer of mutual fund units may fall under the residual clause of the treaty`s capital gains article. Under this provision, such gains may be taxable only in the country where the investor is resident, potentially allowing eligible UAE residents to claim exemption from Indian capital gains tax.
The availability of treaty relief depends on the specific circumstances and the applicable legal provisions.
Documents Required to Claim Tax Treaty Benefits
NRIs seeking benefits under the India-UAE DTAA should ensure that they meet the relevant eligibility requirements.
These may include obtaining a valid Tax Residency Certificate (TRC) issued by the UAE Federal Tax Authority for the relevant period and furnishing Form 10F, where required.
Investors should also verify their residential status under Indian tax law and maintain supporting documents relating to their investments, transactions and capital gains.
Revised Return Deadline for FY 2024-25 Has Expired
The deadline for filing a a revised income-tax return for FY 2024-25 (Assessment Year 2025-26) was December 31, 2025. Taxpayers can no longer correct errors for that assessment year through the regular revised-return facility.
However, eligible taxpayers may consider filing an ITR-U to correct an incorrectly claimed exemption on capital gains from Indian shares, subject to the applicable statutory conditions and restrictions.
Additional Tax and Interest May Apply
When filing an updated return, taxpayers must report the taxable capital gains and pay the resulting tax and applicable interest, including interest under Sections 234B and 234C, where applicable.
An additional income-tax payment may also be required. For an updated return filed during FY 2026-27, the additional income tax is generally 25% of the aggregate tax and interest payable. Higher rates may apply depending on when the updated return is filed.
What NRIs Should Check Before Filing ITR-U
NRIs should review their capital gains calculations, confirm their eligibility for treaty benefits and determine whether they can legally file an updated return. Consulting a qualified tax professional can help prevent further errors and ensure compliance with Indian tax regulations.
The key point is that capital gains from Indian shares and mutual fund units may receive different treatment under the India-UAE tax treaty. Investors should assess each category separately rather than claim a blanket exemption on all capital gains.
Top Stories
-
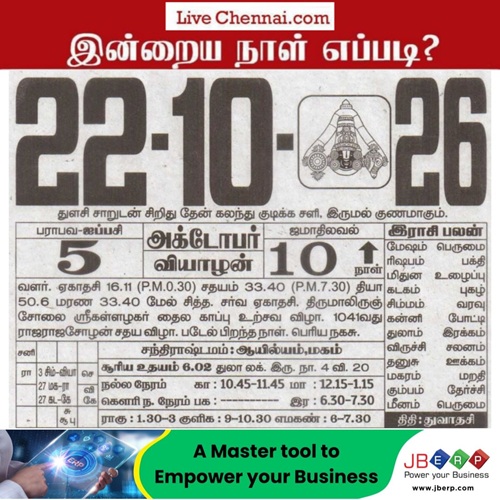 Tomorrow Panchangam October 22, 2026 | Auspicious Timings, Rahu Kalam, Gulikai21/Oct/2026 5:48:35 PM
-
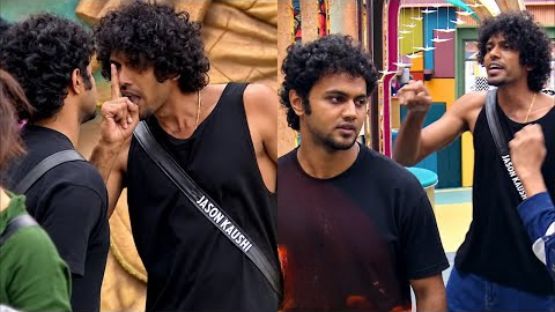 Bigg Boss Tamil 10: Avinash Challenges Jason as Team Leadership Clash Escalates21/Oct/2026 5:10:02 PM
-
 Selling Old Gold Jewellery? 5 Tips to Get the Best Price21/Oct/2026 4:58:38 PM
-
 Cognizant Leases 6.45 Lakh Sq Ft Office Space in Chennai for ₹303 Crore21/Oct/2026 4:53:24 PM
-
-
 Chennai Rain Alert: Heavy Rain Likely Until October 25 as Low-Pressure System Moves North21/Oct/2026 4:31:39 PM
 JB Soft System