Fixed vs Floating Interest Rate: Which Loan Interest Option Should You Choose?
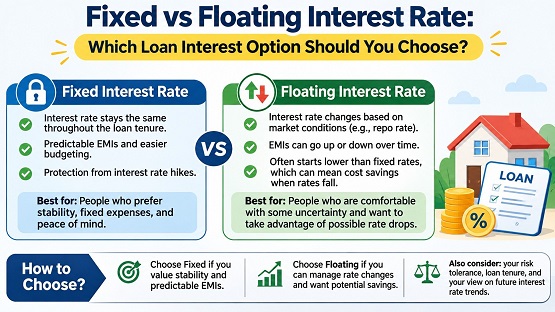
When applying for a home loan or other long-term borrowing facility, customers often need to choose between fixed and floating interest rates. Understanding the difference can help borrowers select a repayment option that suits their financial situation.
What Is a Fixed Interest Rate?
A fixed interest rate remains unchanged for the agreed fixed-rate period. This allows borrowers to plan their monthly repayments with greater certainty.
For example, if a loan carries a fixed interest rate of 9% during the agreed period, the applicable rate will generally remain the same during that period, subject to the loan agreement.
The main advantage is predictable repayment planning. However, borrowers may not automatically benefit if market interest rates fall.
What Is a Floating Interest Rate?
A floating interest rate changes according to the applicable benchmark and lender`s interest rate terms.
If the benchmark rate increases, the borrower`s interest rate may rise. If it decreases, the interest rate may fall.
Floating-rate home loans linked to external benchmarks can reflect RBI Repo Rate changes, subject to contractual reset provisions.
Key Differences Between Fixed and Floating Rates
Fixed Rate:
- Offers greater repayment predictability.
- Protects against rate increases during the fixed period.
- May not provide immediate benefits when market rates fall.
Floating Rate:
- Changes according to benchmark movements.
- Can benefit borrowers when interest rates decline.
- May increase repayment costs when interest rates rise.
Which Option Is Better?
The right choice depends on income stability, loan tenure, risk tolerance and expectations about future interest rates.
Borrowers should compare the applicable rate, reset conditions, conversion charges and prepayment rules before signing the loan agreement.
Understanding both options can help individuals make more informed borrowing decisions.
Top Stories
-
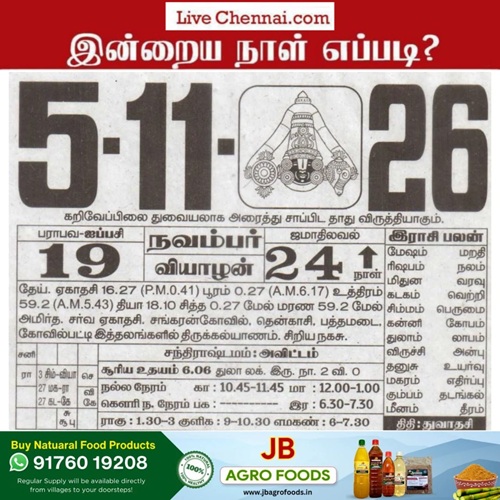 Tomorrow Panchangam November 05, 2026 | Auspicious Timings, Rahu Kalam, Gulikai04/Nov/2026 5:51:57 PM
-
-
 Annan Seer Scheme 2026 - 27: Tamil Nadu Issues Tender for 60,000 Gold Coins and Silk Sarees04/Nov/2026 5:02:33 PM
-
 6 Best Marriage Temples in Chennai - Wedding Booking Guide | Watch Full Video04/Nov/2026 5:01:20 PM
-
 OpenAI Doubles ChatGPT Pro Work and Codex Usage Limits for Pro 100 and Pro 500 Plans04/Nov/2026 4:56:24 PM
-
 Real Estate Channel Partner Meeting in Chennai on November 5, 6, 202604/Nov/2026 4:52:30 PM
 JB Soft System