What should NRIs do with their Indian bank account after moving abroad?
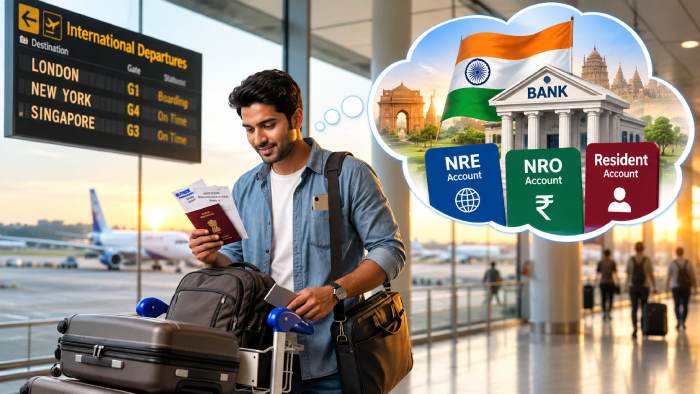
What should NRIs do with their Indian bank account after moving abroad?
Moving abroad can change how you should manage your existing Indian bank account. If you become an NRI, it is important to review your account status and determine whether it needs to be redesignated or converted into an appropriate NRI account. Understanding the difference between an NRI account in India and an NRO account can help you manage your finances while remaining compliant with applicable requirements.
Can you continue using your existing Indian bank account?
You should not assume that a regular resident savings account can simply continue unchanged after your residential status changes.
When you become an NRI, inform your bank and review the account according to the bank`s applicable procedures. Depending on your circumstances, the existing account may need to be redesignated as an NRO account or you may need to open another appropriate NRI account.
Taking this step can help ensure that your banking arrangements reflect your current residential status.
What happens to your existing savings account?
Your existing resident savings account may need to be converted or redesignated once you become an NRI.
An NRO account is generally used to manage permitted income arising in India, such as:
-
- Rental income
-
- Pension
-
- Dividends
-
- Interest income
-
- Other permitted Indian-source income
If you continue to receive Indian income after moving abroad, an NRO account can provide a suitable account structure for managing those receipts.
When should you consider NRO account opening?
NRO account opening may be relevant when you need to manage Indian-source income after becoming an NRI.
You may consider an NRO account if you:
-
- Receive rental income from property in India
-
- Receive pension or other eligible income in India
-
- Earn dividends or interest from Indian investments
-
- Need to make regular payments in India
-
- Want to keep Indian-source income separate from overseas earnings
The exact requirements and treatment of different income sources depend on applicable regulations and bank terms.
Do you also need an NRE account?
An NRE account serves a different purpose from an NRO account.
|
Account type |
Common purpose |
|
NRE account |
Managing eligible overseas earnings in India |
|
NRO account |
Managing permitted income arising in India |
If you earn abroad and regularly transfer eligible foreign earnings to India, an NRE account may be suitable for those funds. An NRO account can then be used for permitted Indian-source income.
Maintaining both can help separate different sources of funds and make your financial arrangements easier to manage.
How can digital banking help after you move abroad?
Managing an NRI account in India remotely can be easier when the bank provides internet and mobile banking facilities.
Depending on the bank and account type, digital banking may allow you to:
-
- Check account balances
-
- Monitor incoming income
-
- Transfer funds
-
- Pay permitted bills
-
- View account statements
-
- Receive transaction alerts
-
- Manage routine banking requirements from abroad
This can reduce the need for branch visits and make it easier to manage Indian financial commitments while living overseas.
Conclusion
Moving abroad does not mean you have to abandon your Indian banking arrangements, but it does mean you should review them. Informing your bank, updating your residential status and considering an NRO account for permitted Indian-source income can help keep your finances organised. An NRE account may complement this arrangement when you also need to manage eligible overseas earnings. When reviewing an NRI account in India, comparing digital facilities, charges, documentation and repatriation conditions can help you choose an arrangement suited to your circumstances.
FAQs
1. What should I do with my Indian bank account after becoming an NRI?
Inform your bank about the change in residential status and check whether your existing resident account needs to be redesignated or converted into an appropriate NRI account.
2. Should I convert my existing account to an NRO account?
If you continue to receive permitted income arising in India, an NRO account may be appropriate. The bank can confirm the applicable process and requirements.
3. Can I keep an NRE and NRO account together?
Eligible NRIs may maintain both account types, subject to applicable regulations and bank requirements. They can be used for different sources of funds.
4. Can I manage an NRI account from abroad?
Many banks provide internet and mobile banking facilities that allow eligible customers to manage an NRI account in India remotely.
5. What is required for NRO account opening?
NRO account opening may require documents such as a passport, visa or overseas residence proof, address proof, PAN and other KYC or tax-related information. Requirements vary by bank and applicant.
Top Stories
-
 Tomorrow Panchangam October 09, 2026 | Auspicious Timings, Rahu Kalam, Gulikai08/Oct/2026 5:51:14 PM
-
 Gold Loan vs Home Loan: Which Is Better for Urgent Financial Needs?08/Oct/2026 5:39:41 PM
-
 JB SOFT SYSTEM Helps Organisations Build Custom Community Portals08/Oct/2026 5:30:07 PM
-
 Arupadai Veedu Murugan Temple, Besant Nagar, Chennai08/Oct/2026 5:24:35 PM
-
 Flipkart Big Billion Days Sale: Poco Phones Get Up to Rs. 6,000 Discount08/Oct/2026 4:59:38 PM
-
 2026 Honda Elevate Facelift: Price, Variants, Colours and Features08/Oct/2026 4:50:12 PM
 JB Soft System